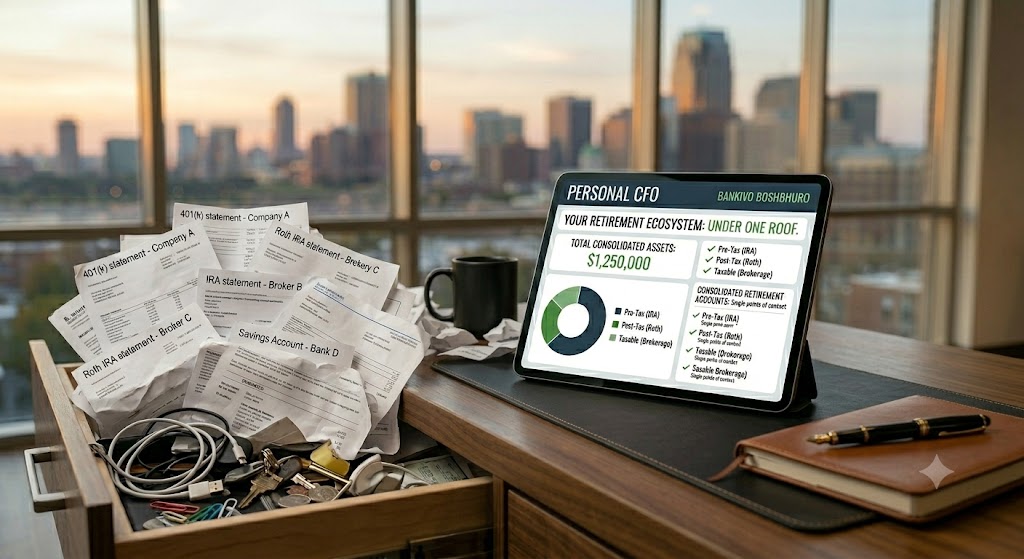
Over the course of a successful 30+ year career, it is incredibly common to accumulate a financial “junk drawer,” which is why consolidating retirement accounts must be a top priority. You might have an old 401(k) from a previous employer, a rollover IRA at one brokerage, a Roth IRA at another, and a handful of forgotten bank accounts.
During your working years, leaving these accounts scattered might have felt harmless. But as you enter the “Red Zone”—the critical years just before and after retirement—complexity becomes a massive liability.
As your Personal CFO, our goal is to help you experience a “Metanoia”—a fundamental change in thinking about your wealth. In the Accumulation Zone, your primary goal was simply investing money wherever you could. In the Distribution Zone, your goal is generating a reliable, tax-efficient paycheck while protecting against sequence of returns risk.
You cannot execute a seamless income strategy if your money is scattered across six different platforms. Here is why consolidating retirement accounts is one of the most critical steps in your transition.
The Danger of Delaying Consolidating Retirement Accounts
When your assets are decentralized, it is nearly impossible to understand what you actually own. A scattered portfolio typically leads to two major risks:
-
Accidental Concentration: You might think you are diversified, but if three different mutual funds across three different accounts all heavily invest in the exact same tech stocks, you are taking on hidden, concentrated risk.
-
Tax Inefficiency: Without a unified view, you cannot strategically harvest tax losses or optimize your asset location, leaking valuable dollars to the IRS.
3 Reasons for Consolidating Retirement Accounts
When we build a comprehensive financial life plan, we act as the integrator. We bring your assets under one roof for three critical reasons:
1. Clarity for Your 3 Tax Buckets
Successful retirement income planning requires coordinating your Taxable, Tax-Deferred, and Tax-Free accounts. If your pre-tax money and post-tax money are disorganized and spread across multiple institutions, we cannot easily execute advanced strategies like Roth Conversions or dynamic spending. Consolidating retirement accounts gives us a clean dashboard to pull the right dollar, from the right tax bucket, at the right time.
2. Consolidating Retirement Accounts Avoids the RMD Trap
When you reach age 73, the IRS forces you to start taking Required Minimum Distributions (RMDs) from your pre-tax accounts. If you have multiple IRAs scattered across different brokers, you must calculate and manage the RMD for each account separately. If you miscalculate or forget one, the IRS penalty is severe. By consolidating into a single IRA, you have one simple calculation and one clean distribution to manage.
3. Protecting Your Surviving Spouse
One of our primary jobs as a Personal CFO is protecting your family from the “Widow’s Penalty.” When one spouse passes away, the surviving partner is forced to navigate a season of profound grief. The absolute last thing they need is to play detective, tracking down statements, passwords, and advisors for half a dozen forgotten accounts. Consolidation is an act of love and financial stewardship. It ensures your surviving spouse has one trusted point of contact and total clarity over their future.
Upgrade Your Financial Infrastructure
Retirement should be a season of clarity, not administrative headaches. If your financial life is currently fragmented into silos, you are carrying the burden of being the expert who coordinates all the pieces.
It is time to delegate the complexity.
Click here to schedule a Fit Call and let your Personal CFO declutter your financial life today.