For thirty or forty years, your financial life operated on a predictable rhythm, but leaving the workforce successfully requires a proactive retirement paycheck strategy to replace that security. You went to work, received a paycheck, paid your bills, and saved the rest. However, as you enter the “Red Zone”—the critical five years before and five years after you retire—that familiar rhythm comes to an abrupt halt. Suddenly, you face the intimidating task of turning off your salary and turning on your portfolio. As a fee-only fiduciary financial planner, I specialize in retirement income planning and do my best work with people in or near retirement. I frequently see retirees struggle with this exact transition. To move smoothly from accumulator to spender, you simply need a structured retirement paycheck strategy.
What Is a Retirement Paycheck Strategy?
A retirement paycheck strategy is a coordinated system that converts your accumulated retirement accounts, pensions, and Social Security benefits into a predictable, automated monthly income stream. This approach minimizes lifetime taxes and buffers against market volatility. Instead of taking random withdrawals whenever you need cash, a structured retirement paycheck strategy recreates the steady, familiar cash flow of your working years. Consequently, you can step into retirement with total clarity, knowing your monthly bills are covered regardless of short-term market headlines.
At Metanoia Financial, we construct this strategy by organizing your income into three distinct operational engines:
| Engine | Income Source | Strategic Purpose |
| 1: Income Floor |
Social Security & Pensions |
Covers your core, non-negotiable monthly living expenses. |
| 2: The War Chest |
Cash, CDs, Short-Term Treasuries |
Protects your portfolio from sequence of returns risk. |
| 3: Growth Engine |
Globally Diversified Portfolio |
Outpaces inflation to maintain your purchasing power over time. |
Engine 1: Establishing Your Guaranteed Income Floor
The foundation of your income plan begins with your lifetime guaranteed income sources. This includes Social Security benefits, traditional pensions, or reliable annuities. The primary goal is to cover as much of your core, non-negotiable living expenses as possible with these guaranteed checks.
Crucially, deciding when to claim Social Security plays a major role in this engine. Delaying your claim up to age 70 can increase your monthly benefit by approximately 32% compared to your Full Retirement Age benefit. You can learn more about how delayed retirement credits are calculated directly from the Social Security Administration. Optimizing this timing provides a higher, inflation-adjusted income floor for the rest of your life.
Engine 2: Funding a Liquid “War Chest”
Once we establish your guaranteed income floor, we look at the gap between that floor and your total desired monthly spending. However, drawing directly from equities during a market downturn creates a severe hazard known as sequence of returns risk. In retirement, it is not just about the average returns you get; it is about when you get them. If the stock market drops 20% in your first year of retirement and you are forced to sell shares to generate cash, you dig a hole in your principal that is mathematically very difficult to climb out of.
To neutralize this danger, we build a liquid “War Chest” containing one to three years of your living expenses in safe, liquid assets like cash, CDs, or short-term treasuries. For more information on how we prioritize cash reserves, read our Foundational Discipline & Cash Flow Guide. If the market experiences a severe correction, we pause equity sales and pay your monthly income directly out of your War Chest until the market recovers.
Engine 3: The Growth Engine for Long-Term Purchasing Power
Because retirement can easily last thirty years or more, inflation acts as a silent thief, eroding your purchasing power over time. Therefore, maintaining a globally diversified portfolio of great companies is essential to outpacing rising costs. Financial science has taught us that the market is an effective information-processing machine. Consequently, we embrace market pricing and avoid market timing. We primarily utilize DFA and Vanguard sub-advised mutual funds because they effectively capture the returns of target asset classes.
Generating income from your growth portfolio requires precise tax coordination across your 3 Tax Buckets: Taxable, Tax-Deferred, and Tax-Free. You can review the specifics of this framework in our Proactive Tax Strategy Overview. Drawing income in the wrong order can trigger unnecessary tax brackets or cause sudden spikes in your Medicare premiums, known as IRMAA surcharges. By strategically coordinating distributions, your plan maximizes your net after-tax spendable income.
Automating Your Retirement Paycheck Strategy
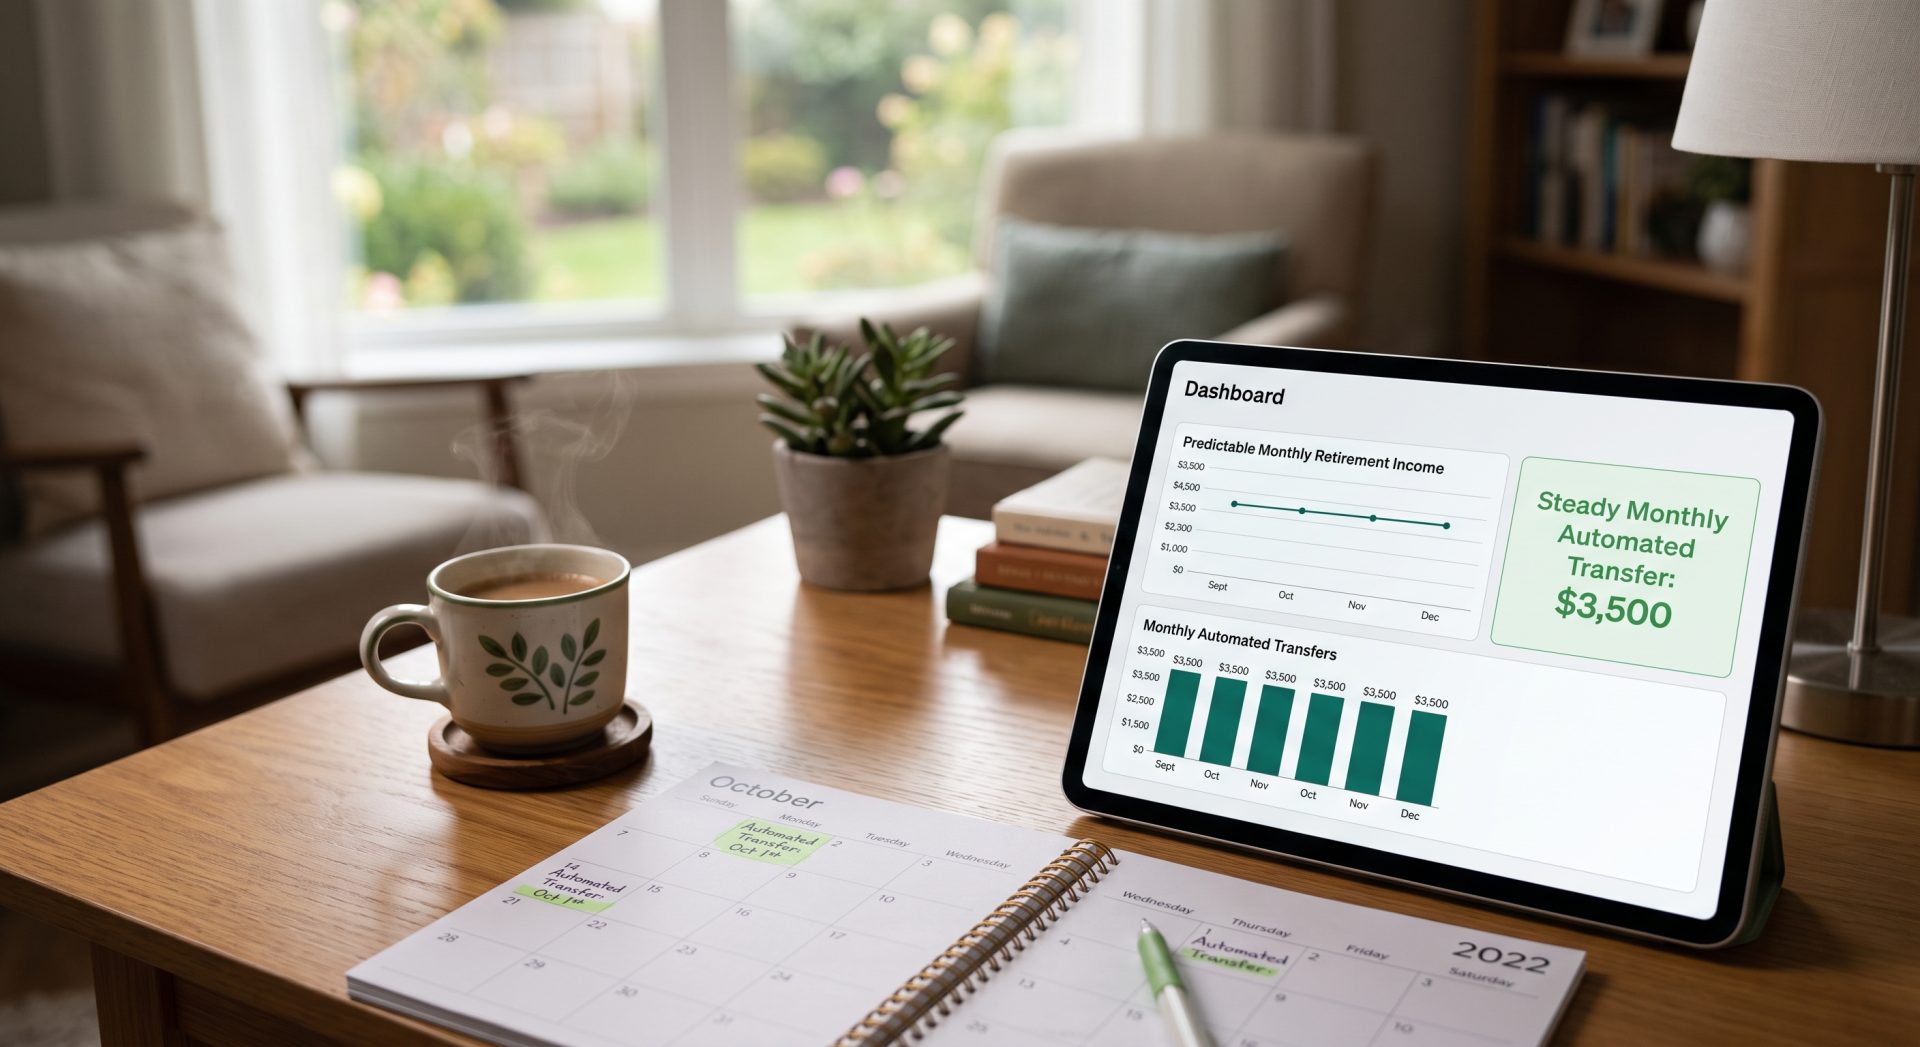
The ultimate goal of a retirement paycheck strategy is to eliminate administrative headaches and emotional stress. Once we establish your plan, we automate the entire process. On the 1st of every month, an automated transfer lands directly in your primary checking account. Furthermore, we recommend that our clients use Charles Schwab & Co., Inc. as the qualified custodian to safely hold assets and facilitate these transfers.
When the inevitable storms of life come your way and threaten to knock you off course, I will be there as a friend, coach, encourager, expert, and trusted advisor to help navigate the course and protect you from knee-jerk emotional decisions. Transitioning from saving to spending is one of the most significant psychological adjustments you will ever make. If you are ready to turn off your W-2 salary and establish a stress-free automated income system, we invite you to connect with us.