
The Retirement Bridge Years: Funding the Gap Before Medicare
For many successful professionals, the dream is to step away from their primary career while they are still young and healthy enough to enjoy the fruits of their labor. However, retiring at 60 or 62 introduces a unique financial challenge: navigating the retirement bridge years. This is the critical window of time after your W-2 paycheck stops, but before you become eligible for Medicare at age 65 or reach your maximum Social Security benefit at age 70.
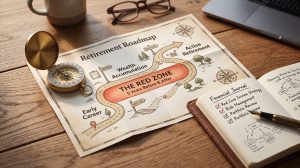
As a fee-only fiduciary financial planner, my role as your Personal CFO is to help you experience a “Metanoia”—a fundamental shift in how you view your wealth. In the Accumulation Zone, your job was simply to grow your portfolio. Now, as you enter the Red Zone (the five years before and after retirement), your focus must shift to generating reliable, tax-efficient income.
If you are planning an early exit, here is how we build a comprehensive financial life plan to safely cross the retirement bridge years.
Managing Healthcare in the Retirement Bridge Years
The most immediate challenge of early retirement is health insurance. Because Medicare is not available until age 65, you must proactively secure private coverage.
-
The Options: You might utilize COBRA for the first 18 months, transition to a spouse’s workplace plan, or purchase a policy on the Affordable Care Act (ACA) exchange.
-
The Risk: Healthcare premiums can be unexpectedly high. Furthermore, this is the exact stage in life—around age 60—where we strongly advise evaluating Long-Term Care (LTC) insurance to protect your portfolio from catastrophic custodial care costs down the road.
Because ACA subsidies are frequently tied to your taxable income, a Personal CFO can help you strategically manage your withdrawals. By keeping your taxable income lower, we can potentially qualify you for significant health insurance premium reductions during your retirement bridge years.
Funding the Gap: The “War Chest” Strategy
When your salary stops, how do you pay your bills while letting your investments continue to grow? The answer lies in establishing foundational discipline and cash flow.
Instead of randomly selling stocks to generate cash, we construct a liquid “War Chest”. We set aside one to three years of your living expenses in safe, stable assets like cash, short-term Treasuries, or CDs. If the stock market experiences a severe drop early in your retirement, we pause equity sales entirely. Instead, you draw your living expenses directly from this War Chest. Consequently, this strategy neutralizes “Sequence of Returns Risk” and prevents you from permanently locking in market losses.
| Asset Category | Purpose During Bridge Years | Metanoia Strategy |
| The “War Chest” (Cash/Short-Term) | 1-3 years of living expenses | Fund the gap when W-2 income stops; protect against market crashes. |
| Tax-Deferred (Traditional IRA) | Low-income “Tax Valley” management | Execute strategic Roth conversions up to the top of low tax brackets. |
| Growth Engine (Equities) | Long-term inflation protection | Leave globally diversified equities alone to compound and recover. |
The Massive Tax Opportunity of the Bridge Years
While the retirement bridge years present cash flow challenges, they also offer one of the most powerful tax planning opportunities of your life.
Because your W-2 income has stopped, but your Required Minimum Distributions (RMDs) and Social Security have not yet begun, you are likely sitting in a temporary “tax valley”. We use this low-income window to proactively execute strategic Roth Conversions.
By intentionally moving funds from your tax-deferred Traditional IRA to your tax-free Roth IRA, you pay taxes today at historically low rates. Ultimately, this secures 100% tax-free growth and distributions for the rest of your life, protecting you from future tax hikes and Medicare IRMAA surcharges down the road. You can review the official distribution guidelines directly on the IRS Retirement Plans page.
Evidence-Based Investing During the Transition
Even in retirement, your money needs to outpace the silent thief of inflation. To achieve this, we do not attempt to outguess the market or chase past performance. Financial science has taught us that the market is an effective information-processing machine, processing billions of dollars in trades every single day.
By utilizing institutional-class funds, we structure globally diversified portfolios. We systematically target higher expected returns through Small Cap, Value, and High Profitability dimensions. Staying disciplined and fully invested ensures you capture the market’s best days, which drive long-term wealth compounding.
A Season for Biblical Stewardship
Finally, true financial peace comes from recognizing that your wealth is a tool entrusted by God to fund life goals, care for family, and practice radical generosity. The retirement bridge years are a perfect time to integrate tax-smart generosity tools like Donor-Advised Funds (DAFs). Giving with a “warm hand” allows you to witness the joy your wealth creates for your family and your church while you are still here.
You have worked diligently for decades to reach the finish line. Do not let an uncoordinated income plan jeopardize your early retirement.
As your Personal CFO, guiding clients through the Red Zone and across the retirement bridge years is the proactive planning my team (including Cherice and Abby) does every day. Our 100% remote practice model allows us to seamlessly serve families in St. Louis, and across the nation.
Click here to schedule a Fit Call with your Personal CFO today.